National Pension System

The National Pension System (NPS) is a government-regulated retirement savings scheme that helps individuals build a retirement corpus through market-linked investments. Subscribers can contribute towards their retirement savings, choose from available investment options and receive benefits according to the applicable withdrawal rules. The scheme is regulated by the Pension Fund Regulatory and Development Authority (PFRDA).

Lowest Management Fees (0.01%)

Maximize your returns with institutional-grade costs.

tax-free

Tax-Free Lump Sum Withdrawal

Enjoy tax exemptions on your maturity corpus.

Compound Growth through Equity & Bonds

Benefit from flexible asset allocation for higher growth.

Top performing fund managers

Quick Details About the National Pension System

This table gives a quick overview of the NPS and its features for readers who want the essential details before exploring the rules.

Feature Details
Full form National Pension System
Regulator Pension Fund Regulatory and Development Authority (PFRDA)
Main purpose Long-term retirement savings and pension planning
Eligible applicants Eligible Indian citizens, including resident and non-resident Indians, and Overseas Citizens of India (OCI), subject to the relevant model's rules
All Citizen Model entry age 18 to 85 years, subject to eligibility and KYC requirements
Account types Tier I and Tier II, subject to eligibility
Investment options Common Schemes with Active Choice or Auto Choice, and other schemes offered under the applicable framework
Returns Market-linked; not guaranteed
Contributions Can generally be made regularly or as required, subject to the applicable scheme's terms
Withdrawal Depends on the subscriber's model, scheme, exit reason, corpus and applicable regulations
Tax benefits Available subject to the tax law, eligible contribution type and tax regime applicable to the subscriber
Account identifier Permanent Retirement Account Number (PRAN)

What is the National Pension System?

The National Pension System is a defined-contribution retirement savings scheme that allows eligible subscribers to invest towards their retirement. The amount accumulated depends on contributions, the selected investment options, market performance, applicable charges and the withdrawal route chosen at exit. NPS also offers tax benefits in specified circumstances, subject to the applicable tax rules.

The Pension Fund Regulatory and Development Authority (PFRDA) regulates NPS, while the NPS Trust oversees the interests of subscribers and the management of the scheme in accordance with the applicable framework. Central Recordkeeping Agencies (CRAs) maintain subscriber records and provide account-related services. Each subscriber receives a Permanent Retirement Account Number (PRAN), which helps identify and manage their NPS account. As NPS investments are market-linked, returns and the final retirement corpus are not guaranteed.

How NPS Works?

Once you open an NPS account, you receive a Permanent Retirement Account Number (PRAN) to identify your account. Your PRAN generally remains associated with you when you change jobs or locations. You make contributions according to the applicable rules, and the money is invested through your selected NPS investment option and pension fund manager. The portfolio may include equity, corporate debt, government securities and other permitted asset classes, depending on the option selected.

As your investments earn returns year after year, your money benefits from compounding, meaning you earn returns not just on your investment but also on the returns already generated. At the time of exit, a part of your total savings is paid to you as a lump sum, while the remaining amount is used to provide a regular monthly pension.

To understand the impact of starting early, consider this example. Assume an annual return of 12%. If you start investing ₹5,000 per month at age 30 and continue till 60, your total investment of ₹18 lakh can grow to around ₹1.76 crore. Now compare this with starting later. If you begin at age 40 and invest ₹10,000 per month (double the amount), your total investment of ₹24 lakh will grow to only about ₹1 crore by age 60.

This clearly shows that starting early gives your money more time to compound, resulting in a much larger retirement corpus even with a lower monthly investment.

National Pension System Calculator See Your Expected Maturity Amount

₹

Expected Rate of Return

%
6% 20%

Your NPS Maturity Summary

Total Investment
₹18,00,000
Total Maturity Amount
₹67,24,222
Breakup of Maturity Amount
Annuity ₹13.45 L
Lumpsum ₹53.79 L
% Maturity amount you want as lumpsum
%
Which gives you
Lumpsum (80%)
₹53.79 L

Fully Tax Free

₹40.35 L tax free

divider-icon
Income for life
₹7,845/month
from 13.45 L invested in annuity @7% p.a.
Start NPS Now!

What are the Key Features of NPS?

NPS offers several advantages that make it attractive for retirement planning:

Example
Market-linked Returns:
Unlike fixed-income plans, NPS invests partially in equities, which have historically yielded higher returns (around 9-12% annualised). Over decades, even small contributions can grow into a large corpus through compounding.
Example
Low Costs:
NPS has one of the lowest expense ratios in the industry. Pension fund managers charge only about 0.01-0.30% per year (depending on the scheme), whereas mutual funds typically charge 1-2%. This means more of your money stays invested.
Example
Partial Withdrawals:
You can withdraw portions of your Tier I contributions before retirement for specific needs (up to 25% of your contributions, for events like education, marriage or medical emergencies) after a minimum of 3-5 years. This provides some flexibility without compromising long-term goals.
Example
Portability and Flexibility:
Your Permanent Retirement Account Number stays with you for life, even if you change jobs or cities. NPS also lets you switch between fund managers once a year and choose how much equity vs debt you hold
Example
Government Regulation:
NPS is regulated by PFRDA, ensuring strict oversight and transparency.

What are the Asset Classes in NPS?

When you enroll in NPS, your money does not sit idle in a bank vault. It is strategically invested across specific asset classes to balance high growth with capital preservation. Below are the four asset classes that your money is spread across:

  • Asset Class E (Equity): Investments in shares of listed companies. This class carries higher risk but offers the highest potential for long-term wealth creation.
  • Asset Class C (Corporate Debt): Investments in fixed-income instruments issued by robust corporate entities. This provides moderate returns with moderate risk.
  • Asset Class G (Government Securities): Investments in bonds issued by state and central governments. This is the safest asset class and guarantees capital protection.
  • Asset Class A (Alternative Assets): Investments in real estate investment trusts, infrastructure funds, and alternative investment funds.

PFRDA has strict guidelines and regulations for investment limits in each asset class to protect your retirement funds from excessive risk.

Asset Class Tier I Maximum Cap Tier II Maximum Cap
Equity (E) Up to 75% Up to 100%
Corporate Debt (C) Up to 100% Up to 100%
Government Securities (G) Up to 100% Up to 100%
Alternative Assets (A) Up to 5% Not permitted

What are the Investment Types in NPS?

While investing in NPS, you have two different ways to choose how your money is distributed among the 4 asset classes mentioned above:

Example
Active Choice

With Active Choice, you have full control over where your money is invested. You can decide how much goes into equity (shares), corporate bonds, and government securities. This option is suitable if you understand how markets work and want to actively manage your portfolio. For example, younger investors who are comfortable with higher risk can invest up to 75% in equity under the Tier I account.

Example
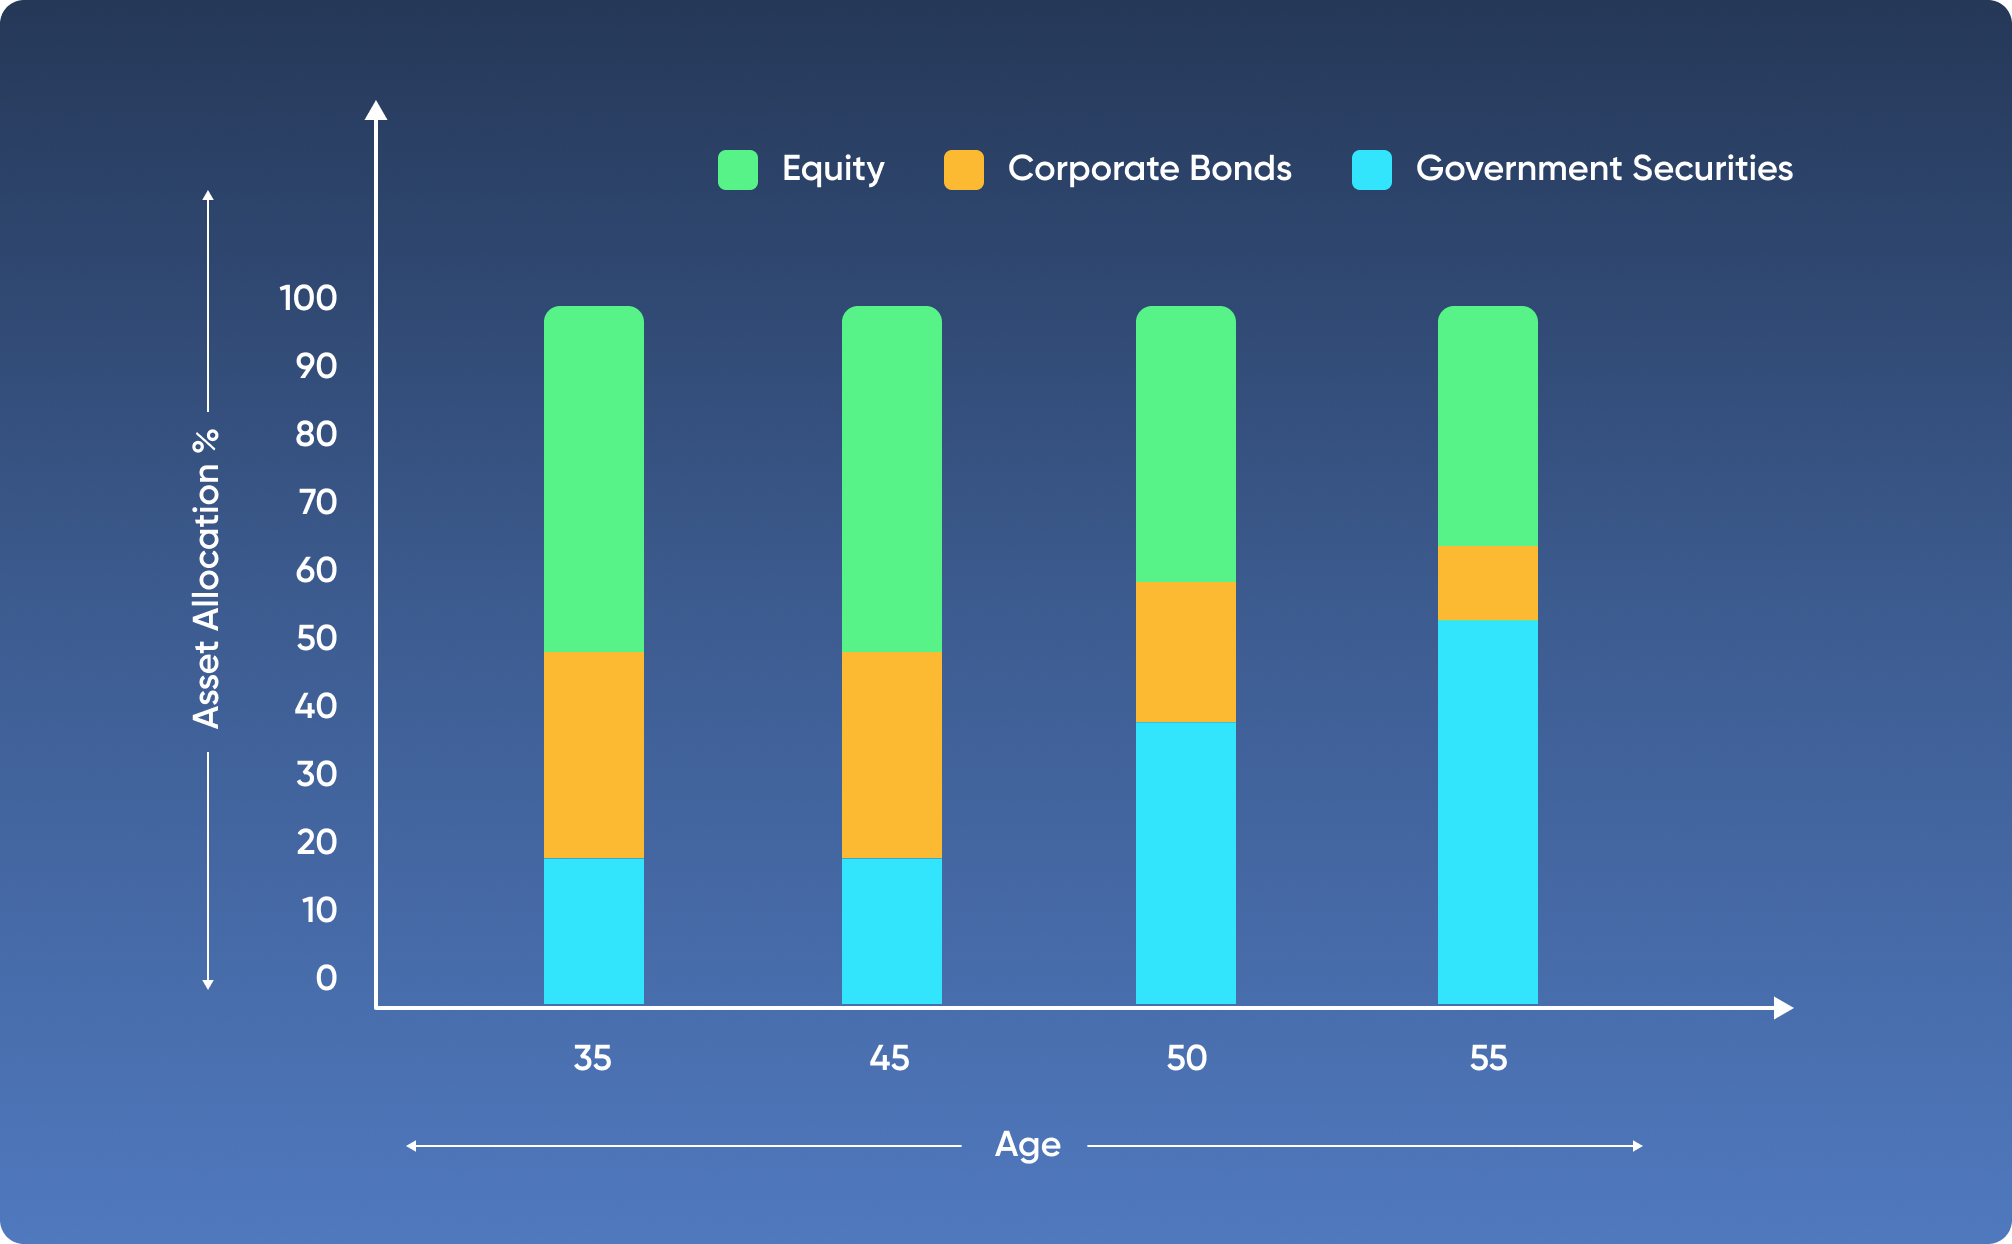
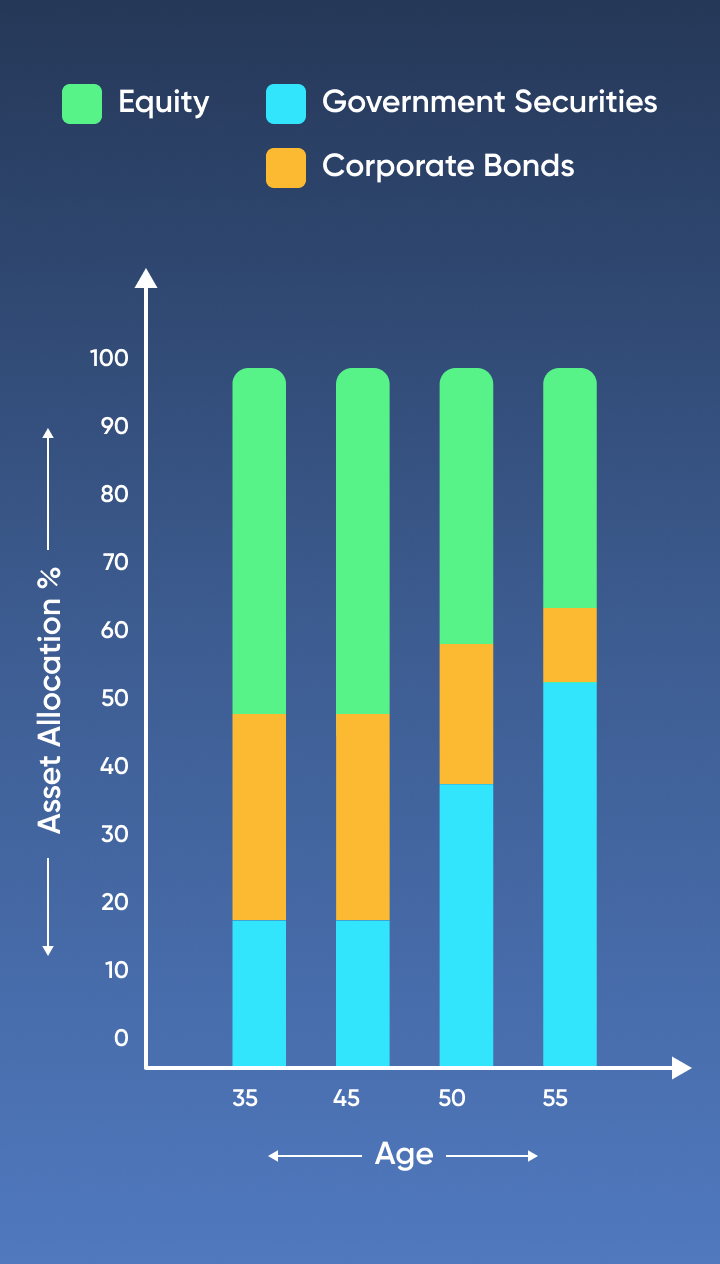
Auto Choice

Auto Choice is a simpler, hands-off option for NPS investment. Here, your investments are managed automatically based on your age. You can select from different lifecycle funds, and the system will gradually reduce your exposure to equity as you grow older. Over time, more of your money is shifted to safer options like government bonds, helping protect your savings as you approach retirement.

Assest Allocation Assest Allocation

Who Can Open an NPS Account?

The National Pension System is open to eligible individuals who want to build retirement savings through regular contributions. Under the All Citizen Model, Indian citizens living in India or abroad, as well as Overseas Citizens of India (OCIs), can voluntarily open an NPS account, subject to the prescribed eligibility and Know Your Customer (KYC) requirements.

NPS Eligibility Criteria

To open an NPS account under the All Citizen Model, an applicant must meet the following conditions:

  • Age: The applicant must be between 18 and 85 years old.
  • Citizenship: The applicant must be an Indian citizen, whether resident or non-resident, or an Overseas Citizen of India.
  • KYC compliance: The applicant must complete the applicable identity and address verification requirements.
  • Legal capacity: The applicant must be legally competent to enter into a contract under Indian law.
  • Individual account: NPS is an individual pension account. It cannot be opened in one person's name on behalf of another person.

Hindu Undivided Families (HUFs) and Persons of Indian Origin (PIOs) are not eligible to subscribe under the All Citizen Model. Eligibility conditions may differ for specific NPS models, so applicants should check the rules applicable to their category before enrolling.

NPS for NRI and OCI Subscribers

Non-Resident Indians (NRIs) and Overseas Citizens of India (OCIs) can also join NPS under the All Citizen Model, subject to the applicable onboarding and KYC requirements. They need to provide the relevant identity, address and bank account documents during registration.

NRIs may be required to provide an Indian passport, while OCIs must provide their OCI card. Applicants must also provide the applicable proof of address and details of an eligible Indian bank account, such as an NRE or NRO account. The exact documentation and applicable conditions should be confirmed against the current subscriber registration requirements.

What are the Specialised NPS Variants?

NPS has different models to serve individual subscribers, employees covered through participating employers and children investing through NPS Vatsalya. Each model has its own eligibility and operating rules.

  1. NPS All Citizen Model

    The NPS All Citizen Model is designed for eligible individuals who want to save for retirement independently of an employer-sponsored NPS arrangement. It can suit salaried individuals, self-employed professionals, freelancers and other eligible subscribers. Subscribers can select a pension fund and an investment approach in accordance with the scheme's rules.

  2. NPS Vatsalya

    NPS Vatsalya is a specialised system designed exclusively for minors. Parents or guardians can open an account in the child's name and start investing early. Once the child turns 18, the account automatically becomes a regular Tier I account, allowing the investment to continue without interruption.

  3. Corporate NPS

    Corporate NPS allows eligible employees to join NPS through an employer that has adopted the scheme. Depending on the employer's policy, contributions may come from the employee, the employer or both. Employer contributions may also qualify for tax benefits under the applicable rules, making this model relevant to employees reviewing their workplace retirement benefits.

  4. NPS Sanchay

    PFRDA introduced NPS Sanchay in May 2026 under the All Citizen Model and Multiple Scheme Framework. NPS Sanchay is intended to accommodate people such as farmers, agricultural workers, artisans, shopkeepers, drivers, freelancers and other eligible self-employed or informal-sector workers. Read the dedicated NPS Sanchay scheme guidance for its investment design, contribution process and exit conditions before enrolling.

What are the NPS Withdrawal Rules?

NPS withdrawal rules determine when you can access your retirement savings and whether a portion of your accumulated corpus must be used to purchase an annuity. The applicable conditions depend on factors such as your subscriber category, age, accumulated corpus and reason for withdrawal.

The main withdrawal options in NPS are:

Exit Type Condition Withdrawal Allowances and Rules
Partial Withdrawal Permitted after 3 years for specific needs (medical, housing, education) Up to 4 times before age 60 (with a 4-year gap). Up to 3 times after age 60. Maximum 25% of your own contributions per withdrawal.
Premature Exit Voluntary exit at any time before completing 15 years or reaching age 60 The 5-year lock-in is removed. If corpus is ₹5 lakh or less, 100% full withdrawal is allowed. If above ₹5 lakh, up to 20% lump sum, minimum 80% to annuity.
Normal Exit Completing 15 years of subscription or reaching age 60 (whichever is earlier) If corpus is ₹8 lakh or less, 100% full withdrawal is allowed. If above ₹8 lakh but up to ₹12 lakh, up to 80% lump sum, minimum 20% to annuity. If above ₹12 lakh, up to 80% lump sum, minimum 20% to annuity.

NPS subscribers may also have options to receive eligible lump-sum withdrawals in instalments or defer their exit, subject to the applicable rules.

For a detailed breakdown of withdrawal limits, corpus thresholds, annuity requirements, tax treatment and the online withdrawal process, read our NPS Withdrawal guide.

NPS Reforms of 2025-26: What Changed?

The 2025-26 reforms made NPS more flexible for non-government subscribers. The Multiple Scheme Framework (MSF) came into effect from 1 October 2025, allowing a choice of schemes with different risk levels. Eligible non-government subscribers can now withdraw up to 80% of their corpus at normal exit, with at least 20% going to an annuity, while the 60%/40% split continues for government-sector subscribers. The five-year lock-in on premature exit under the All Citizen Model has been removed, the maximum entry and exit age is now 85, partial withdrawal rules have been revised, and subscribers can take financial assistance against up to 25% of their own contributions.

What Are the Charges and Fees in NPS?

NPS charges cover account onboarding, recordkeeping and investment management. The amount depends on the subscriber category, account balance and service channel.

Charge Type Applicable Charge How It Is Deducted
PoP onboarding ₹200 per PRAN; may be ₹100 for eligible fully digital onboarding Deducted in quarterly instalments through cancellation of units
Annual PoP charge 0.20% of assets under management (AUM) per year Adjusted through NAV and deducted quarterly; no charge on dormant accounts
CRA account opening Up to ₹18 for an e-PRAN or ₹40 for a physical PRAN card Deducted from the account, where applicable
CRA annual maintenance Private-sector NPS: ₹100-₹500 per account per year, based on the corpus slab. Government-sector NPS: up to ₹100 per account per year Deducted from the account or borne by the employer, as applicable
CRA transaction charge ₹0 under the current prescribed schedule No transaction fee under this charge head
Pension fund management fee Private-sector NPS: 0.12%, 0.08%, 0.06% or 0.04% per year, depending on the pension fund's AUM slab. Government-sector NPS: 0.09%, 0.06%, 0.05% or 0.03% per year, depending on the AUM slab Reflected in the scheme's NAV
Custodian charge 0.000000001770% per year of assets under custody Reflected in NAV

What are the NPS Tax Benefits

NPS offers strong tax benefits, but the actual savings depend on the tax regime you choose - old or new. Each regime treats your contributions differently, which can impact both your tax savings and overall returns.

Understanding how NPS works under both tax regimes helps you make better decisions, so you can maximise your take-home income while also building a stronger retirement fund.

Tax Section Benefit Description Old Tax Regime Status New Tax Regime Status Maximum Deductible Limit
Section 80CCD(1) Employee / Self contribution (within 80C) Available Not Available Up to 10% of basic salary + DA (or 20% of GTI for self-employed), capped at Rs 1.5 lakh overall 80C limit
Section 80CCD(1B) Exclusive extra deduction over 80C Available Not Available Up to Rs 50,000 extra deduction
Section 80CCD(2) Employer's contribution to employee NPS Available Available Up to 10% of basic salary + DA for private employees (14% for govt employees). Aggregate Rs 7.5 lakh employer contribution cap across PF/Superannuation/NPS
Section 10(12A) Tax exemption on 60% lump sum exit Tax-Free Tax-Free 60% of total accumulated corpus
Section 10(12B) Tax exemption on partial withdrawals Tax-Free Tax-Free Up to 25% of self-contributions
Example
Old Tax Regime

Under the Old Tax Regime, salaried individuals can claim tax deductions of up to ₹2 lakh on their own NPS contributions. This includes up to ₹1.5 lakh under Section 80CCD(1) (which is part of the overall 80C limit and includes options like PPF, EPF, and ELSS) and an additional ₹50,000 under Section 80CCD(1B). Apart from this, your employer can also contribute up to 10% of your basic salary plus DA to your NPS account. This contribution is fully tax-deductible under Section 80CCD(2) and is over and above the ₹2 lakh limit.

For self-employed individuals, the rules are slightly different. You can claim up to 20% of your Gross Total Income under Section 80CCD(1), subject to the ₹1.5 lakh limit under 80C. In addition, you can claim an extra ₹50,000 under Section 80CCD(1B), taking the total possible deduction to ₹2 lakh

Example
New Tax Regime

Under the New Tax Regime, you cannot claim tax deductions on your own NPS contributions. This means the benefits under Section 80CCD(1) and the additional ₹50,000 under Section 80CCD(1B) are not available.

However, the employer contribution benefit under Section 80CCD(2) is still available and remains one of the biggest advantages of NPS in the new regime. Salaried employees can receive tax-free contributions from their employer of up to 10% of their basic salary plus DA (up to 14% for central and state government employees). This benefit is over and above the standard deduction allowed in the new tax regime.

Note: It is important to know that across both tax regimes, there is a combined limit of ₹7.5 lakh per year on employer contributions to Provident Fund, Superannuation Fund, and NPS. If this limit is exceeded, the extra amount is treated as a taxable benefit in the hands of the employee.
Types of NPS Accounts

There are two types of NPS accounts: Tier I and Tier II. The Tier I account is the main retirement account. It is mandatory, comes with tax benefits, and has restrictions on withdrawals to help you save for the long term.

The Tier II account, on the other hand, is optional and works like a flexible investment account, similar to a mutual fund. You can withdraw money from it anytime, but it does not offer special tax benefits.

Feature Tier I Account Tier II Account
Purpose Long-term retirement savings Flexible voluntary investment
Who can open Any eligible Indian citizen (18 to 70) Anyone with an active Tier I account
Minimum to open ₹500 ₹1,000
Minimum per year ₹1,000 None
Withdrawal freedom Strictly regulated lock-in Fully flexible at any time
Tax on contribution High tax deductions under Section 80CCD No tax deductions
Tax at exit Up to 60% tax-free lump sum Taxed as per income slab
Lock-in period Until age 60 or 15 years of joining No lock-in period

To open a Tier II account, you must first have an active Tier I account. While Tier I helps you stay disciplined with long-term savings, Tier II gives you the flexibility to invest extra money and access it whenever needed.

How to Open an NPS Account?

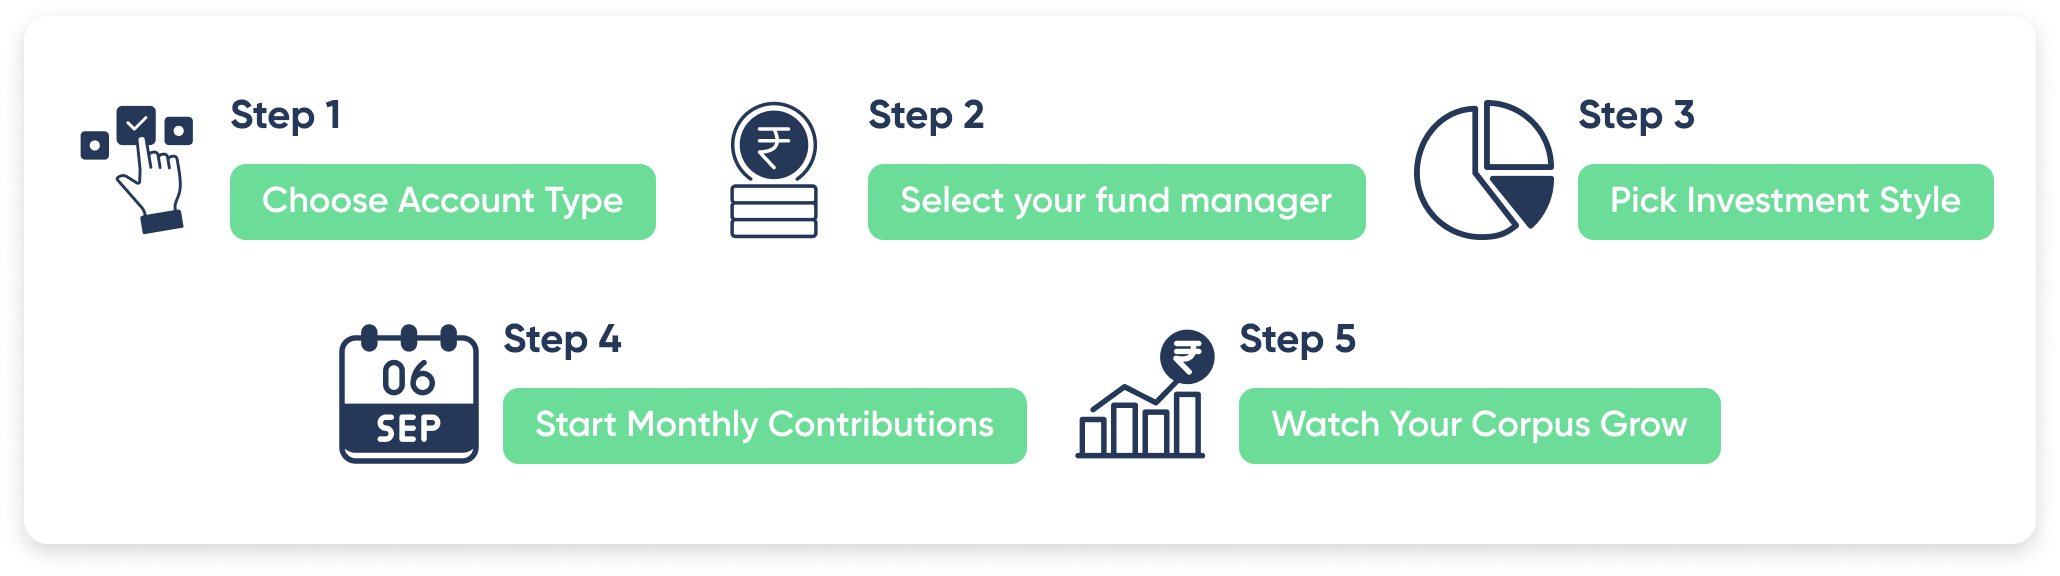
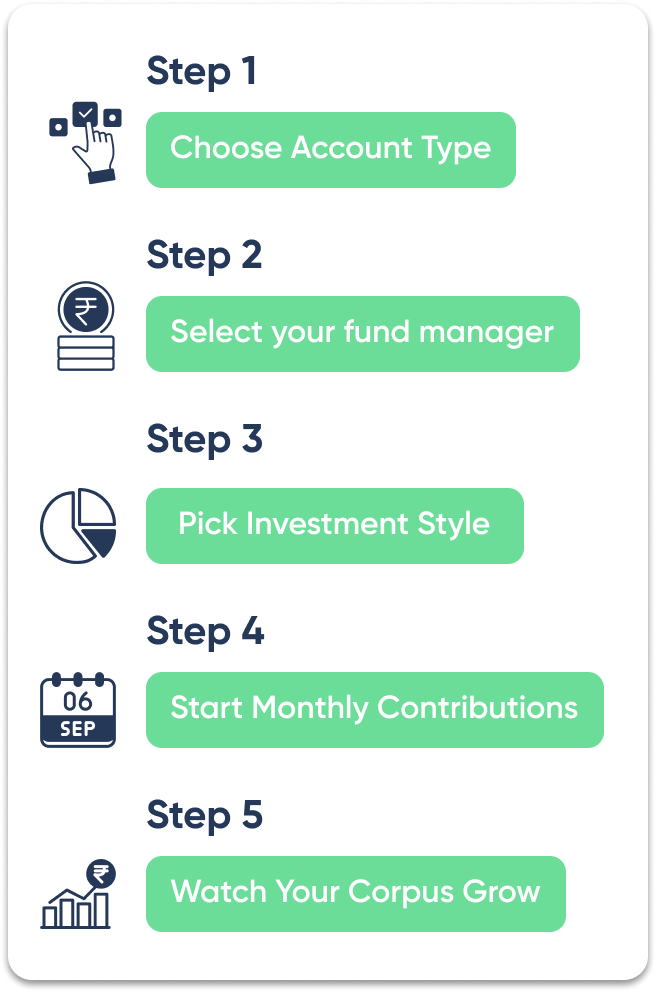
Opening an NPS account with PensionBazaar is as simple as it gets. You can start your retirement journey in less than a minute directly through the dedicated portal at https://nps.pensionbazaar.com.

Example
Here is the exact step-by-step process to open your NPS account on PensionBazaar:
  1. Mobile Verification: Visit https://nps.pensionbazaar.com/ and enter your 10-digit mobile number. Ensure this mobile number is linked to your Aadhaar card for quick OTP verification.

  2. Customise and Compare Plans: Enter your age, monthly investment amount, and investment duration (such as 15 years). PensionBazaar instantly displays comparative benchmark returns and total corpus projections across top Pension Fund Managers including Kotak Pension Fund, ICICI Prudential Pension Fund, Tata Pension Fund, and Axis Pension Fund. Select your preferred scheme and click Invest Now.

  3. Enter Basic Details: Provide your full name as per your PAN card, PAN number, email address, and date of birth. Tick the consent box to authorise downloading your KYC records seamlessly from the Central Registry of Securitisation Asset Reconstruction and Security Interest of India (CERSAI) or DigiLocker.
  4. CKYC Verification: Enter the One-Time Password received from CERSAI on your mobile phone to complete instant paperless CKYC verification.
  5. Profile and Nominee Details: Verify your pre-filled personal details, select your marital status, place of birth, annual salary range, and occupation sector. Enter your nominee's name, date of birth, relationship, and allocation percentage (up to 100%).
  6. Self Declaration: Confirm your residential status and tax details for Indian residency compliance.
  7. Contribution and Payment: Review your selected fund scheme, set up auto-debit for automated monthly contributions if desired, and complete your first contribution of ₹500 or more using UPI, Debit Card, or Net Banking.
open desk icon open desk icon

Documents Required to Open an NPS Account

To open an NPS account, you generally need identity and address proof, PAN details, a photograph, a signature and bank account information. The exact requirements depend on your subscriber category and registration method.

Document Detail Purpose
PAN card Identity verification and tax-related records, where applicable
Aadhaar or other accepted identity and address proof KYC verification
Photograph and signature Subscriber identification and registration
Bank account details Contributions and eligible withdrawal payments
Mobile number and email address OTP verification and account communication
Passport and overseas-status documents, where applicable Additional verification for NRI and OCI subscribers

Additional documents may be required depending on whether you are a resident Indian, NRI, OCI, government employee or corporate subscriber.For the step-by-step process, read our guide to opening an NPS account.

NPS vs EPF, PPF, Mutual Funds and Fixed Deposits

NPS, EPF, PPF, mutual funds and fixed deposits serve different financial goals. While NPS is designed to help build retirement savings, EPF primarily supports salaried employees, PPF offers long-term government-backed savings, mutual funds provide market-linked investment options, and fixed deposits offer a more predictable return. The right choice depends on your investment horizon, risk tolerance, liquidity needs and tax situation.

Feature NPS EPF PPF Mutual Funds (ELSS) Fixed Deposits
Returns Market-linked (8% to 14%) Fixed by govt (approx 8.1%) Fixed by govt (approx 7.1%) Market-linked (10% to 15%) Fixed by bank (6% to 7.5%)
Tax Benefit on Investment (Old Regime) ₹1.5L (80C) + ₹50K (80CCD(1B)) + 80CCD(2) ₹1.5L (80C) ₹1.5L (80C) ₹1.5L (80C) ₹1.5L (5-yr Tax Saving FD under 80C)
Tax Benefit on Investment (New Regime) Deduction under 80CCD(2) only No tax deduction No tax deduction No tax deduction No tax deduction
Tax on Maturity (Both Regimes) 60% lump sum is 100% tax-free Completely tax-free Completely tax-free 12.5% LTCG tax above ₹1.25L gain Fully taxable as per individual tax slab
Liquidity & Lock-in 15 years or age 60 Linked to employment 15-year lock-in 3-year lock-in Fixed term (5 years for tax saving)
Cost Extremely low (Fund fee max 0.12%) Nil administrative cost to employee Nil cost Moderate (Expense ratio 0.5% to 1.5%) Nil cost
Check your NPS balance Check your NPS balance

Is NPS the Right Choice for You?

Choosing whether to invest in NPS depends on your financial goals and how disciplined you are with long-term savings. If you want a safe and regulated option that helps you build a retirement fund while also offering tax benefits under both the old and new tax regimes, NPS can be a good choice. It combines the stability of traditional provident funds with the growth potential of market-linked investments.

Recent changes have made NPS more flexible, including the option to exit after 15 years under certain conditions. It also offers very low fund management charges, clear and transparent investment allocation, and the flexibility to switch between higher-risk equity and safer government bonds.

If your goal is to build a retirement corpus that can beat inflation and provide a steady income after retirement, starting early with NPS can be a smart financial decision.

nps facts

FAQs About Nation Pension System

Yes. Following the December 2025 reforms, you can execute a normal exit after completing 15 years of subscription. Additionally, the 5-year lock-in for premature exit has been removed entirely, allowing you to voluntarily exit at any time, subject to specific annuity purchase conditions.

Yes. While individual self-contribution deductions under Section 80CCD(1) and 80CCD(1B) are not available under the New Tax Regime, employer contributions under Section 80CCD(2) remain 100% tax-deductible up to 10% of basic salary. Furthermore, the 60% lump-sum maturity withdrawal remains completely tax-free under the New Tax Regime.

You can switch your investment preference seamlessly through your online dashboard. Subscribers are allowed to change their investment choice (Auto to Active, or adjust asset allocations) up to four times in a financial year.

Once you reach maturity and purchase an annuity, the contract is fixed with the chosen Annuity Service Provider (ASP). You cannot change the provider after annuity payments commence, so it is vital to compare rates carefully at the time of exit.

No, you cannot take a direct loan against your accumulated corpus. However, you are permitted to make partial withdrawals up to 25% of your own contributions for specific financial obligations like medical care, higher education, or housing.

If a subscriber passes away, the nominee can withdraw 100% of the corpus as a lump sum completely free of tax under both the Old and New Tax Regimes. Alternatively, they can opt to purchase an annuity or use Systematic Lump-sum Withdrawal (SLW) routes.

Your PRAN is fully portable. It stays with you regardless of job changes, sector shifts, or city relocations. You simply update your employment details in the system, and your new employer can begin contributing to the exact same account under Corporate NPS

faq-isolation
Profile

Retirement is not the end of earning

- it's the beginning of living on your own terms

India is at a turning point. A growing middle class, longer lifespans, and rising aspirations mean that how we plan for our later years has never mattered more. Yet most of us are underprepared. PensionBazaar exists to close that gap - with clarity, simplicity, and the right plan for every stage of life. Your future self deserves nothing less.

Vishwajeet Goel Linkedin - Leadership Team, PensionBazaar

article

calender-icon 27 Oct 2026
Pradhan Mantri Viksit Bharat Rozgar Yojana

The Pradhan Mantri Viksit Bharat Rozgar Yojana (PMVBRY) is a government sch...

article

calender-icon 27 Oct 2026
Ladli Laxmi Yojana

Ladli Laxmi Yojana is a social welfare scheme launched by the Government of...

article

calender-icon 22 Oct 2026

What Is Tax Liability?

Tax liability is the amount of income tax a taxpayer needs to pay for a financial year after ...

article

calender-icon 05 Oct 2026

Sukanya Samriddhi Yojana Online Payment

Sukanya Samriddhi Yojana Online Payment Sukanya Samriddhi Yojana is a small savings...

article

calender-icon 05 Oct 2026

What is Commuted Pension?

Retirement planning involves a decision on how to receive the pension. The ...

article

calender-icon 01 Oct 2026

Where to Invest After Retirement?

Retirement marks the beginning of a new phase of life. It offers you time f...